

Ava Finance

- 1.69K Reviews
- 4.7
- Downloads
- 500,000+
Our take on Ava Finance from Appgk
Managing credit on a phone can feel either refreshingly simple or frustratingly vague, depending on how clearly an app explains what you are doing. I spent time with Ava Finance as a finance app from Ava Finance, Inc., focusing not only on its credit-building purpose but also on how it behaves during ordinary mobile moments: checking in between errands, waiting for a page to load, or trying to recover after a weak connection. My overall impression is that it is most useful for someone who wants a guided credit routine rather than a traditional banking dashboard.
The app is free to get started and is rated for Everyone, which makes it approachable for a broad audience. It has also attracted a 4.7 average from around 17 thousand ratings, with more than 500 thousand installs. Those figures suggest that the concept is resonating, but they do not remove the need to understand how the experience fits your own financial habits. Building credit is gradual, and an app cannot replace careful budgeting, timely payments, or checking your wider financial picture.
How the credit-building experience feels on a phone
The first thing I noticed is that Ava is designed around repeated, short interactions rather than long financial sessions. That matters because credit-related tasks are easier to maintain when they fit into an existing routine. I could imagine opening it after being paid, before reviewing monthly bills, or while checking whether a planned purchase still fits my budget. It feels less like a full bank replacement and more like a focused companion for people who need structure around credit.
That focus is also the app’s main trade-off. If you want detailed spending categories, broad account aggregation, investing tools, or a complete view of household cash flow, a conventional banking app or budgeting service may be a better center of gravity. Ava makes more sense when the question is, “What should I do next to stay on track with credit?” rather than, “Can I manage every part of my financial life here?”
Best Parts of Ava Finance
Things to Keep in Mind About Ava Finance
The developer, Ava Finance, Inc., has kept the product centered on the promise expressed by its store summary: building credit quickly. I would treat the word “quickly” carefully. It communicates the app’s goal, not a guarantee that every person will see the same result on the same schedule. Credit outcomes depend on personal circumstances and the information used by credit systems, so I would use the app as a tool for consistent behavior, not as a shortcut around the process.
Where connectivity becomes part of the experience
Because this is a finance app, network access is not a minor convenience. When I am checking a credit-related status or moving through an account action, I expect the app to communicate with its online service. A connection problem can therefore interrupt something that feels more important than a delayed social feed. Even if the interruption lasts only a moment, uncertainty about whether an action completed is uncomfortable when money or credit is involved.
News and Features Related to Ava Finance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
This is especially noticeable in places where mobile service changes quickly: underground transit, crowded venues, elevators, rural roads, or the edge of a building. A screen that loads partially can leave you wondering whether to try again. My practical advice is to avoid repeating an action immediately when the connection drops. First check whether the screen has updated, then look for a confirmation or refreshed status before attempting anything again. That small pause can prevent duplicated effort and unnecessary confusion.
I would also avoid making an important credit check while rushing through a poor-signal area. Ava is better used when you can give the session a few uninterrupted moments. That does not mean every visit needs to be planned like a banking appointment, but it does mean connectivity should be treated as part of the workflow. Open the app before you need an answer, allow pages to finish loading, and do not assume that a blank or stalled screen means nothing happened.
Don't want to read the full review?
Everyday mobile situations where it fits well
A realistic use case is a person who has recently started paying more attention to credit but does not want to study financial terminology every evening. They might open Ava during a lunch break, review the current guidance, and make a note of the next action they need to remember. The value is not just in that single session; it is in turning a vague goal into a repeatable habit.
Another useful moment is before applying for a financial product elsewhere. I would not use Ava as the only source of information before making a serious decision, but it can serve as a prompt to review whether my credit-building routine is active and whether I have overlooked a payment obligation. The app is most helpful when it encourages preparation rather than impulsive applications.
Screenshots
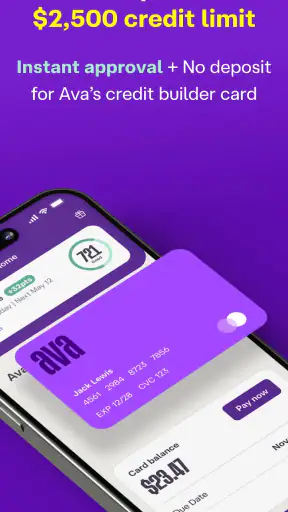
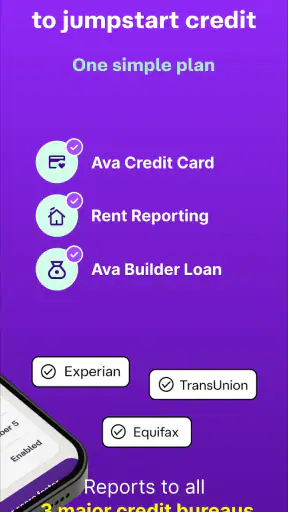
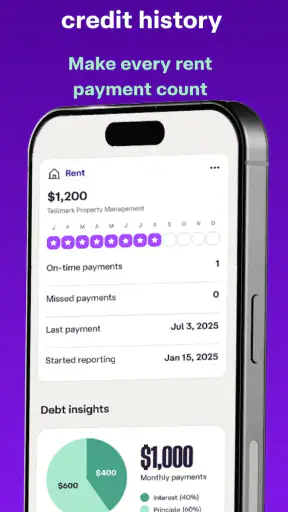
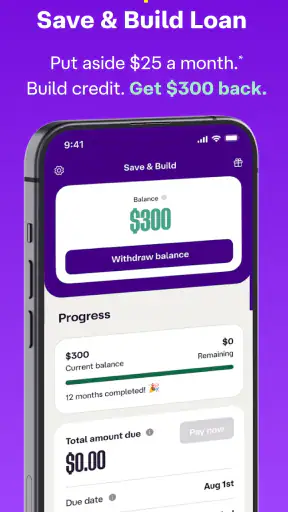
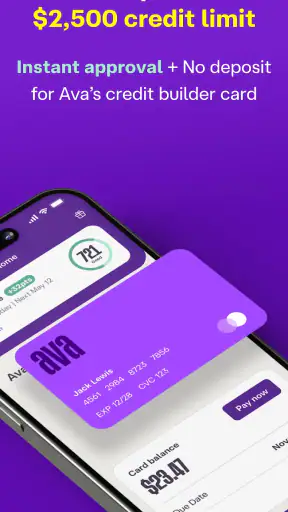
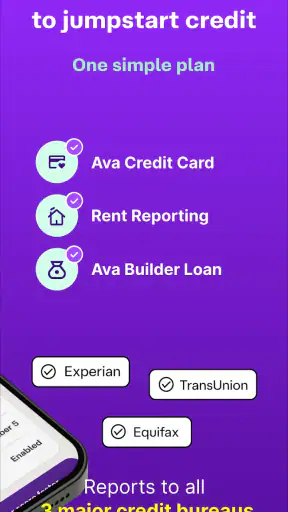
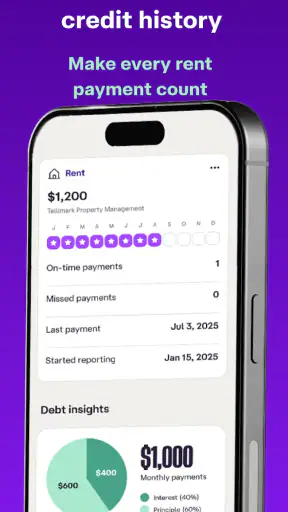
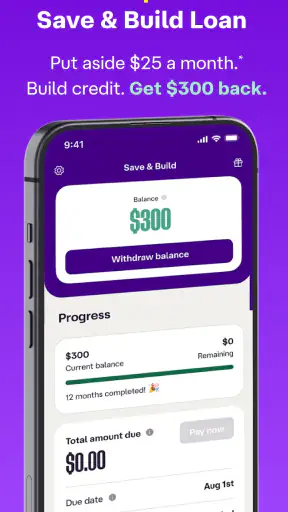
It can also suit someone who shares a phone with a busy schedule and needs a quick, focused check instead of a lengthy desktop session. The mobile format makes it easier to build the review into a morning or evening routine. The weakness is that a phone is also full of distractions. If I open the app while multitasking, I am more likely to skim an instruction or close the screen before understanding what is required. For financial tasks, a short focused session is better than checking while distracted.
Travel creates a more complicated case. When I am moving between networks, I would prefer to review information before leaving reliable coverage rather than depend on a last-minute check. I would not assume that every important function is available without a connection, so I would plan around online access. That is a sensible habit for any finance app, but it is particularly relevant here because the app’s usefulness depends on current account and credit-related information.
What to do when a session fails or feels incomplete
Connectivity failures are not the only source of friction. A page may take longer than expected, an authentication step may need to be repeated, or an instruction may not be immediately clear. My approach is to separate three questions: did the app open, did the requested action submit, and did the account state update? Those are different events, and treating them as one can lead to unnecessary retries.
If the app stops responding, I would first wait briefly rather than repeatedly tapping. Then I would leave and reopen the relevant screen, checking for a changed status. If the problem continues, I would move to a stronger connection and try again later. For any action that could affect an account or payment, I would keep a personal note of what I attempted and when. That is not glamorous, but it gives you a clear record if you need to explain a confusing sequence.
A useful habit is to take note of the last screen you fully understood before the interruption. For example, if you were reading guidance and the connection failed before any confirmation appeared, treat the action as unresolved until the app shows a clear result. Do not infer completion from a spinner disappearing or from the app returning to a previous page. This cautious workflow is one of the most important practical lessons when using a mobile finance service.
The current version is 5.1.6626, and the app supports devices running Android 9 or later. That gives it a defined compatibility range, but device support alone does not guarantee a smooth session on every phone. Older hardware, aggressive battery management, crowded networks, and outdated system components can all affect how quickly a finance app responds. Keeping the operating system and app current is sensible, especially when the app handles sensitive financial activity.
Using it without wasting mobile data
I would not describe Ava as an app that needs constant attention throughout the day. Its purpose is better served by intentional check-ins. That makes it relatively easy to use in a data-conscious way: open it when you have a reliable connection, complete the task you came for, and close it once the relevant information is clear. There is little benefit in repeatedly refreshing a screen just to watch for a change.
When I am on limited mobile data, I would avoid opening it in the background while moving between locations. I would also wait for Wi-Fi when reviewing several screens or completing setup, particularly if I am already dealing with a weak signal. The goal is not to avoid the app; it is to prevent a half-loaded session from using data while still leaving me without a confident answer.
Data-conscious use also means being thoughtful about where I open a finance app. Public networks can be convenient, but I would prefer a trusted connection for account-related tasks and avoid discussing private financial details in a crowded place. A phone screen is easy for someone nearby to glance at, and a rushed connection can make people focus so much on loading that they overlook their surroundings.
I would not make decisions based solely on a notification or a brief preview. If Ava alerts me to review something, I would open the app when I can verify the complete context. Notifications can be useful reminders, but the full screen is where I would expect to understand what action is actually being requested. This is a small distinction, yet it prevents the common mistake of reacting to a fragment of financial information.
Who will benefit most from the app
Ava is a strong candidate for people who are new to credit-building routines, prefer mobile guidance, and want one focused place to revisit their progress. It may also help users who know that consistency is their weakness. A structured prompt can be more valuable than a spreadsheet if the spreadsheet is never opened.
I would be more cautious about recommending it to someone who already has an established credit strategy and wants advanced analysis across several accounts. That person may get more value from a detailed budgeting platform, a bank’s own tools, or a service that provides a broader financial overview. Ava’s focused design is an advantage for beginners, but it can feel limited if your needs have grown beyond credit-building guidance.
It is also not the right choice for anyone expecting instant transformation. The app can help organize behavior, but responsible credit improvement still requires patience and attention to obligations outside the app. I would not download it with the expectation that simply opening it changes a credit profile. I would download it if I wanted a clearer routine and was willing to follow through.
How it compares with familiar alternatives
The usual alternative is a bank app, which often provides a broader account picture and may already be part of your daily routine. A bank app can be better for balances, transfers, statements, and payments. Ava is more appealing when those general tools do not give enough direction about building credit. In other words, I see them as potentially complementary rather than direct substitutes.
A spreadsheet is another alternative. It offers flexibility and can track exactly what you choose, but it depends entirely on your discipline and understanding of what to record. Ava’s advantage is the dedicated experience: you do not have to design the system from scratch. The trade-off is less freedom than a custom spreadsheet and a greater reliance on the app’s own flow.
Credit-monitoring services may provide alerts or a wider view of credit information, while Ava is oriented toward the practical routine behind improvement. If your priority is spotting changes across a broad credit profile, another service may be more appropriate. If your priority is having a focused mobile companion for credit-building actions, Ava has a clearer reason to exist.
The important comparison is not which app has the most screens. It is which tool you will actually use correctly. A broad financial dashboard that overwhelms you may be less useful than a focused app you check consistently. Conversely, if you need detailed control and already have strong habits, Ava may feel too narrow to justify becoming another regular financial destination.
Small workflow choices that make a real difference
My first practical tip is to create a fixed check-in moment rather than opening the app whenever anxiety strikes. A calm routine makes it easier to distinguish genuine account information from the urge to refresh repeatedly. I would choose a time when I can use a dependable connection and read the entire instruction before acting.
Second, I would keep Ava alongside—not instead of—a broader personal money routine. Before following a credit-related suggestion, I would consider upcoming bills, available cash, and any other financial commitments. This prevents the narrow goal of building credit from pushing a person toward a decision that does not fit their budget.
Third, I would treat interrupted sessions as unfinished until verified. This is particularly important on mobile networks. If a connection drops after tapping a button, I would not immediately repeat the action. I would reconnect, reopen the relevant area, and look for a confirmed state. That workflow is slower by a few seconds but much safer than guessing.
Fourth, I would use the app’s focused nature as a boundary. I would not keep it open while doing unrelated tasks, and I would not interpret every prompt as a reason to make a financial move immediately. The best result comes from using the guidance as part of a considered plan, not as a substitute for judgment.
My verdict on the connected mobile experience
After using Ava as a credit-focused finance app, I see its strongest quality in its narrow purpose. It gives people a reason to return to a credit-building routine without requiring them to construct a complicated system themselves. The free price removes an obvious barrier to trying it, and the Everyone rating makes it broadly approachable. Its reception, including the 4.7 average and roughly 17 thousand ratings, reinforces that many users find the concept useful.
The main limitation is that the app should not be mistaken for a complete financial command center or a guaranteed shortcut. It works best when you have reliable connectivity, a few undistracted minutes, and realistic expectations about how credit develops. Weak networks can make account actions feel uncertain, so I would use it proactively on a trusted connection and verify any interrupted session before trying again.
Ava is worth considering if you want a focused mobile guide for building credit and need help turning intention into regular action. I would skip it in favor of a broader banking or budgeting solution if your main need is comprehensive money management. For the right user, though, its simplicity is not a weakness; it is the reason the app can fit into everyday life. My recommendation is to use it as a consistent credit-building companion, while keeping your wider budget and financial decisions firmly in your own hands.
Ava Finance FAQ
What is Ava Finance and what can I use it for?
Ava Finance is a personal finance application designed to help users organize, monitor, and better understand their money. Depending on the version and available regional features, it may let you view financial information, track spending, manage budgets, and review account activity from one place. Before downloading, check the official listing to confirm which services are supported in your country and whether your bank or financial institution is compatible.
Is Ava Finance safe to use with my financial information?
Ava Finance may require access to sensitive financial details, so security should be considered before connecting any accounts. Review the app’s privacy policy, permission requests, encryption claims, authentication options, and data-sharing practices carefully. Avoid entering information through unofficial download links, use a strong unique password, and enable biometric or two-factor protection if offered. The app should complement—not replace—your own security precautions.
Does Ava Finance connect directly to my bank accounts?
The ability to connect bank accounts, cards, or other financial services depends on Ava Finance’s supported integrations and your location. Some users may be able to link accounts through a secure third-party connection, while others may need to enter transactions manually. Check the current app description and supported institution list before installing. If your provider is unavailable, certain tracking or budgeting features may be limited.
Is Ava Finance free, or does it include subscriptions and extra charges?
Ava Finance’s pricing can vary according to the platform, region, and features included in the current release. The basic download may be free, but advanced tools, premium reports, automated monitoring, or additional services could require a subscription or in-app purchase. Read the pricing details in Google Play or the App Store, paying particular attention to trial periods, renewal terms, and cancellation requirements before starting any paid plan.
Can Ava Finance replace a bank, financial adviser, or budgeting service?
Ava Finance should generally be viewed as a financial organization and monitoring tool rather than a replacement for a bank or qualified financial adviser. It may help you review spending, create better habits, and understand account activity, but its information may not always be real-time or complete. Do not rely on the app alone for investment, borrowing, tax, or other important financial decisions, and verify critical details directly with your provider.











